Short answer
Replacement of domestic items relief lets residential landlords deduct the cost of replacing furniture, furnishings, appliances and kitchenware they provide to tenants. You claim the cost of a like-for-like item plus delivery and disposal, less anything you got for the old one. The first purchase never qualifies, and fixtures fall under the repair rules instead.
Figures checked against GOV.UK and HMRC guidance.
What is replacement of domestic items relief?
It is a deduction from rental income for the cost of renewing moveable items in a let dwelling. It has applied to spending from 6 April 2016 (1 April 2016 for companies), when it replaced the old 10% wear and tear allowance. HMRC manual PIM3210
The relief exists because buying furniture is capital spending, which normally cannot be set against rent. The law makes an exception for replacements only, so the tax follows the real cost of keeping a let home equipped rather than a flat percentage of rent.
It is not limited to furnished lets. A landlord who provides only a cooker and carpets in an otherwise unfurnished flat can claim when those are replaced. HMRC guidance
Which items qualify for replacement of domestic items relief?
HMRC describes domestic items as things for domestic use. The question that sorts most cases is simple: would the item normally leave with the occupant, or is it built into the home?
| Item | How it is treated |
|---|---|
| Sofas, beds, tables, chairs, free-standing wardrobes | Domestic item: this relief |
| Carpets, rugs and curtains | Domestic item: this relief |
| Fridges, freezers, washing machines, televisions | Domestic item: this relief |
| Crockery, cutlery, pans and other kitchenware | Domestic item: this relief |
| Baths, toilets, washbasins, built-in wardrobes | Fixture: repair rules |
| Boilers and water-filled radiators | Fixture: repair rules |
Source: HMRC Property Income Manual, PIM3210. HMRC's list is illustrative, not complete.
Fixtures are not left without relief. Renewing a worn bath or a broken boiler with a similar one is normally a deductible repair, tested in the way our repair or improvement guide explains.
What are the four tests for the relief?
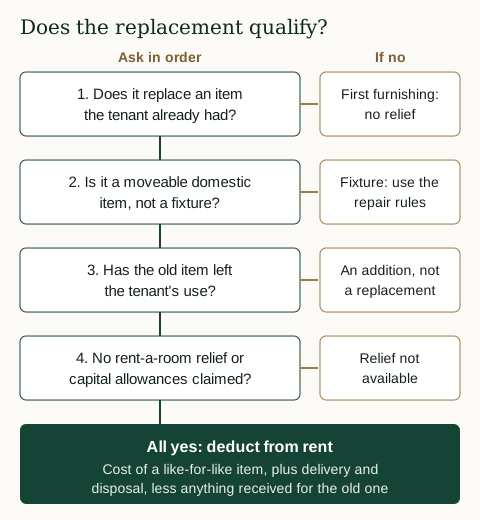
- You let a dwelling. Your property business must include letting a house or flat. Offices and shops are outside the relief.
- It is a true replacement. The new item takes the place of an old one you provided, and is for the tenant's use.
- The old item has gone. It must no longer be available to the tenant. A second fridge added alongside the first is not a replacement.
- No capital allowances. If capital allowances are claimed on the new item, this relief is not available on it.
How much replacement of domestic items relief can you claim?
Start with the price of the new item, but only up to the price of a like-for-like equivalent of the old one. Add incidental costs such as delivery, installation and taking the old item away.
Then take off anything you received for the old item, in cash or as a trade-in.
A reasonable modern equivalent is not an upgrade. A fridge with a better energy rating, or a new budget machine replacing a five-year-old budget machine, qualifies in full.
A real upgrade is capped. HMRC treats an item as an improvement if its function changes or its quality or material is better, such as a sofa bed replacing a plain sofa. You claim only what the plain version would have cost. HMRC guidance
If you part-exchange, the deduction is the cash you actually paid after the trade-in value. HMRC manual PIM3210
Illustrative example
Three replacements in one buy-to-let flat in 2026/27
Assumptions: an individual landlord in England, flat let unfurnished apart from white goods, a sofa and carpets. During the year three items wear out.
| Sofa bed bought for £750; a plain sofa like the old one costs £500 | £500 |
| Delivery of the sofa bed | £40 |
| Less old sofa sold online | (£60) |
| Washing machine of the same standard, fitted and old one removed | £425 |
| Fridge freezer £640, less £90 part-exchange on the old one | £550 |
| Replacement of domestic items relief | £1,455 |
|---|
The extra £250 for the sofa bed gets no relief. At the 20% rate the claim saves £291 of tax; at the 40% rate it saves £582.
Who can and cannot claim the relief?
- Individuals and partnerships letting homes in the UK or overseas can claim it against property income.
- Companies get the same relief for Corporation Tax. Our limited company property accountants include it in company accounts.
- HMO landlords can claim for items in each room and in shared kitchens, where furniture wears out faster. See our HMO accounting service.
- Former holiday lets can use it for spending from 6 April 2025 (1 April 2025 for companies). Any existing capital allowances pool carries on being written down. GOV.UK policy paper
- Rent-a-room lets cannot use it if you claim rent-a-room relief on that home. HMRC manual PIM3210
- Property allowance users cannot either. Claiming the £1,000 allowance replaces all your actual costs, this relief included. GOV.UK
What records support a claim?
An invoice for the new item is rarely enough on its own. Keep a short note of what was replaced, the date, which property it was in and what happened to the old item.
When you upgrade, save a screenshot or quote for a like-for-like model at the time you buy. It is the evidence for the capped figure, and it is hard to recreate years later.
A list of items in each property, updated when you replace one, also makes it easy to show that a purchase was a replacement and not first furnishing. Our rental property bookkeeping keeps this for you.
What mistakes do landlords make with this relief?
- Claiming the first fit-out. Furnishing a flat you have just bought is capital, even when the items are cheap. Only later replacements qualify.
- Claiming the full cost of an upgrade. Only the like-for-like price counts.
- Forgetting the extras. Delivery, fitting and removal of the old item are part of the claim, and are easy to leave out.
- Ignoring the trade-in or sale. Anything you received for the old item reduces the claim.
- Putting a new kitchen through this relief. Fitted units are fixtures, so the repair rules decide the answer.
- Choosing the property allowance by default. In a year with large replacements, actual costs may be worth more. Check before you file your landlord tax return.
The bottom line
Replacement of domestic items relief turns the cost of renewing furniture, appliances and furnishings into a deduction from rent, but only for genuine replacements of moveable items.
Claim the like-for-like price plus delivery and disposal, take off what you got for the old item, and keep a note that shows why the figure is right.
Fixtures and first purchases follow other rules, set out in our guide to landlord allowable expenses. For the wider picture, see how to reduce tax on rental income legally.
Related questions
Can I claim for furnishing a property before the first tenant moves in?
No. The relief covers replacements only, so the first set of furniture and appliances is capital. The pre-letting rule does not help, because it only covers costs that would have been allowable once letting began. HMRC manual PIM2505
Does the relief apply to unfurnished lets?
Yes. It applies to unfurnished, part-furnished and fully furnished homes, as long as you provided the old item for the tenant's use. HMRC guidance
Can I claim for replacing carpets?
Yes. HMRC lists carpets as furnishings, so a like-for-like replacement carpet, including fitting and removal of the old one, qualifies. HMRC manual PIM3210
Is a replacement kitchen covered by this relief?
No. Fitted units and worktops are part of the building, so they are tested as a repair. A kitchen of a similar standard is usually deductible; a larger or better one is usually capital.
What happened to the wear and tear allowance?
It ended when this relief started, from 6 April 2016 (1 April 2016 for companies). It gave fully furnished lets a flat 10% of net rent each year, whether or not anything was replaced. The new relief follows what you actually spend, and covers unfurnished lets too. HMRC manual PIM3200
Official sources
- PIM3210: Replacement of domestic items relief, 2016-17 onwards HMRC Property Income Manual
- PIM3200: Furnished lettings (contents), including replacement of domestic items relief HMRC Property Income Manual
- Work out your rental income when you let property HMRC
- PIM2505: Pre-commencement expenses HMRC Property Income Manual
- Abolition of the furnished holiday lettings tax regime (policy paper) GOV.UK
- Tax-free allowances on property and trading income GOV.UK
Figures were checked against these sources on . Tax rules change: check the source or ask us before acting.
Please note: this guide is general information on UK tax rules at the review date shown. It is not advice for your situation. Rules change and the right answer depends on your circumstances, so check the sources or speak to us before acting.